Category: Uncategorized
- Written by: admin
- Category: Uncategorized
- Published: October 10, 2026
Understanding Dividend Yield
Dividend yield serves as a pivotal financial metric for stock investors, particularly those looking to maximize their return on investment in the form of dividend income. It offers an approximation of the cash flow an investor can anticipate for each dollar invested in a company’s equity. Essentially, the dividend yield quantifies the percentage of a company’s share price that is distributed to shareholders as dividends on an annual basis.
Calculation of Dividend Yield
Understanding the calculation of dividend yield is fundamental for investors who wish to analyze potential investments. The formula to calculate the dividend yield is straightforward:
Dividend Yield (%) = (Annual Dividends per Share / Price per Share) × 100
For example, if a company pays an annual dividend of $3 per share, and the current share price is $100, the dividend yield would be 3%. This simple calculation allows investors to assess the income potential of their investments in comparison to their cost.
Importance of Dividend Yield
The importance of dividend yield cannot be overstated for investors focusing on generating income. For those who prioritize a steady income stream from their investments rather than capital appreciation, dividend yield becomes a crucial factor. It facilitates a comparison of dividend-paying stocks across different sectors and with other investment avenues, such as bonds or savings accounts. By using dividend yield as a benchmark, investors can make more informed decisions about where to allocate their capital.
Assessment of Company Performance
Dividend yield can also offer insights into a company’s performance and how the market values its stock. A high dividend yield might suggest an attractive investment, indicating a high-income opportunity if the stock price seems undervalued. However, investors must tread with caution: a high yield could also be a red flag for underlying financial troubles if the stock price has dropped significantly, thus artificially inflating the yield.
Conversely, a lower dividend yield can indicate a company that focuses on reinvesting earnings into growth opportunities rather than distributing them as dividends. This approach can lead to substantial capital gains in the long term, appealing to investors with a growth-centric investment strategy.
Considerations When Evaluating Dividend Yield
Several key factors should be considered when evaluating dividend yield to ensure a comprehensive investment assessment:
- Payout Ratio: This ratio aids in understanding the sustainability of a company’s dividends. A high payout may signal potential risks if the company cannot maintain dividend payments due to reduced earnings.
- Company Growth: Companies with lower dividend yields might present better long-term returns if they demonstrate robust growth prospects, leading to capital gains.
- Economic Environment: The broader economic landscape, including interest rates and market conditions, can significantly influence dividend yields and stock valuations. In low-interest environments, dividend stocks could become more attractive to investors seeking higher returns.
- Dividend History: A company’s history of consistent dividend payments can indicate its reliability in returning profits to shareholders. Companies with a strong track record of maintaining or increasing dividends over time may provide more stable and predictable income streams.
The evaluation of dividend stocks requires a multifaceted approach that goes beyond simple yield calculations. It is imperative for investors to dive deeper into these factors, examining not only the yields but also the overall health and potential of the business they are investing in. To aid this analysis, various investment platforms and financial advisory services offer comprehensive guides and analytical tools, enabling investors—whether novices or veterans—to make well-informed, strategic decisions.
By leveraging a combination of simple formulas, critical financial ratios, and an understanding of broader economic factors, investors can effectively utilize dividend yield as a tool to optimize their stock portfolios. Furthermore, these insights can help investors align their portfolios with their financial goals, whether they prioritize immediate income or long-term capital growth. Ultimately, informed decisions can lead to more resilient and rewarding investment strategies.
- Written by: admin
- Category: Uncategorized
- Published: October 3, 2026
Understanding the Dividend Payout Ratio
The dividend payout ratio is a financial metric that investors and analysts use to gauge the proportion of a company’s earnings that is distributed to shareholders in the form of dividends. It is a crucial measure for evaluating a company’s financial health, stability, and profitability. This ratio provides insights into how well a company is balancing returning profits to its shareholders versus reinvesting in its growth.
Calculating the Dividend Payout Ratio
Calculating the dividend payout ratio requires the use of a straightforward formula:
Dividend Payout Ratio = (Dividends Per Share / Earnings Per Share) x 100%
This formula indicates the percentage of earnings paid out as dividends. If a company’s earnings per share (EPS) is $5, and it pays $2 in dividends per share, the dividend payout ratio would be 40%.
Why Calculation Is Simpler Than It Seems
While the formula is straightforward, applying it accurately demands a careful understanding of what each component represents. Earnings Per Share (EPS) is a measure of a company’s profitability on a per-share basis and indicates how much money the company is making for each share of stock. It’s crucial to ensure that the EPS used in the formula matches the period of the dividends paid. Similarly, Dividends Per Share reflects the amount of money that’s returned to each shareholder from the company’s profits.
Importance of the Dividend Payout Ratio
Understanding the importance of the dividend payout ratio is crucial for making informed investment decisions. The ratio provides multiple insights into a company’s financial strategies and priorities.
Investor Insight
A higher payout ratio is often attractive to income-focused investors seeking regular income from dividends. These are typically investors who depend on steady, periodic income from their investments, such as retirees. Conversely, a lower payout ratio could suggest that a company is reinvesting more of its earnings into business operations and growth initiatives. This could appeal to growth-oriented investors who are more interested in capital appreciation than immediate income.
Company Health
A company that consistently pays out a high percentage of its earnings might face challenges sustaining these payouts during tough economic times. It’s imperative for investors to assess whether a high payout ratio is sustainable over the long term. A suddenly rising payout ratio could indicate that the company is paying out more dividends than it used to, possibly to attract investors. However, if this strategy isn’t backed by robust earnings growth, it could strain the company’s finances.
How Companies Use the Dividend Payout Ratio
Companies often use the dividend payout ratio as a metric to signal their financial health and strategy to investors. A stable or gradually increasing payout ratio can signal a mature, reliable company that values a steady return to its investors. In contrast, startups or high-growth companies might maintain a low or zero payout ratio, choosing to reinvest earnings into business expansion and development rather than pay dividends.
Comparing Companies Using the Dividend Payout Ratio
It’s insightful for investors to compare the payout ratios of companies within the same industry rather than across different sectors. Industries vary in their typical payout ratios. For instance, utilities and mature sectors often have higher payout ratios compared to technology companies that might prioritize reinvestment over dividends.
Case Studies: Analyzing Dividend Payout Ratios
Consider two companies, both in the consumer goods sector. Company A has a payout ratio of 80%, while Company B maintains a payout ratio of 30%. An income-focused investor might be drawn to Company A due to its higher dividend returns. However, the potential risk is that Company A may not have sufficient retained earnings for significant growth opportunities during economic downtrends. Conversely, Company B’s lower ratio indicates a preference for reinvestment, possibly leading to greater future growth, which might be attractive to long-term and growth-oriented investors.
Factors Influencing Dividend Payout Ratios
Several factors influence a company’s decision on its payout ratio:
Profitability: Companies with stable and high earnings are often in a better position to offer higher dividend ratios.
Cash Flow: Firms with strong cash flows might maintain higher dividend payouts without compromising their operations.
Earnings Expectations: Companies expecting higher future growth might retain earnings to fund potential expansion or to buffer against future uncertainties.
Limitations of the Dividend Payout Ratio
Despite its usefulness, the dividend payout ratio has limitations. It does not account for a company’s future earnings potential or cash flow situations. A declining payout ratio might initially appear problematic but could indicate strategic reinvestment for future growth. Conversely, an increasing ratio might seem promising but could result from unsustainable earnings or temporary profit spikes.
Conclusion
The dividend payout ratio is a fundamental tool used by investors to assess a company’s ability to return profit to shareholders while also supporting its growth and operations. Understanding both the calculation and implications of this ratio is essential for making balanced investment choices. By comparing companies within the same industry and considering external financial conditions, investors can better gauge the suitability of a firm for their investment portfolio. For more detailed financial analysis tools, you may explore financial educational resources available online.
- Written by: admin
- Category: Uncategorized
- Published: September 26, 2026
Understanding Dividend Cover
Dividend cover is a crucial financial metric used by investors and analysts to evaluate the sustainability of a company’s dividend payments. Essentially, it provides valuable insight into a company’s ability to comfortably pay its dividends from its net earnings. Understanding this metric can assist investors in making informed decisions regarding their investment portfolios.
Definition and Calculation
Dividend cover is determined by dividing a company’s net earnings by the dividends that are paid to its shareholders. The formula for this calculation is presented as follows:
Dividend Cover = Net Income / Dividends Declared
By applying this formula, the ratio obtained reveals the number of times a company can afford to pay its current level of dividends using its net income. A higher dividend cover ratio typically suggests that a company is well-positioned to maintain or even increase its dividends. In contrast, a lower ratio can raise concerns about the long-term sustainability of the company’s dividend payouts.
The dividend cover ratio is an important measure for assessing a company’s financial health. It reflects a company’s earnings relative to its dividend obligations, offering a clear picture of whether the company can sustain its dividend policy without risking its financial stability. A key point to remember is that a balance between earnings and dividend payments is critical to safeguarding a company’s financial health.
Interpreting Dividend Cover
It is generally considered that a dividend cover ratio of 2 or more is indicative of a healthy financial state. This suggests that the company’s earnings are at least twice the amount it pays in dividends. Such a scenario signals that the company generates adequate earnings to cover its dividend payouts comfortably.
Conversely, a ratio of less than 1 might suggest a potential risk, indicating that a company is distributing more money in dividends than it actually earns. This situation is not sustainable in the long term unless the company has substantial reserves or resorts to taking on debt. For investors seeking reliable dividend income, a low dividend cover ratio can thus serve as a warning sign.
An important aspect to consider is the volatility of earnings. Even if a company has a strong dividend cover at present, fluctuating earnings can alter this metric considerably. Therefore, it is essential to consider not only the current ratio but also the underlying trends in earnings and how they may impact the dividend cover in the future.
Why Dividend Cover Matters
For investors, the dividend cover ratio is a pivotal metric when considering the potential growth or maintenance of a company’s dividend over time. A strong dividend cover ratio can be an indication of a company’s financial stability and its ability to generate consistent earnings. Consequently, such companies may be attractive choices for investors focused on generating income from their investments.
In stark contrast, companies with a low dividend cover are often vulnerable, as they might struggle to maintain their dividend payouts during periods of declining profits or adverse economic conditions. When faced with such circumstances, companies with insufficient dividend cover may resort to cutting their dividends, potentially leading to negative investor sentiment and a decrease in share price.
Evaluating the dividend cover ratio is, therefore, a part of an investor’s comprehensive assessment process. It is not only about understanding a company’s current financial status but also gaining foresight into its financial capability to reward shareholders in the future. A robust dividend cover is often reflective of good financial management and operational efficiency.
Dividends and Company Strategy
There is considerable diversity among companies in terms of how they manage their dividend cover, influenced heavily by their unique investment strategies. For instance, companies experiencing growth might prefer to reinvest their earnings to harness growth opportunities rather than distributing them to shareholders in the form of dividends. This strategic choice might lead to a lower dividend cover ratio, but it is not necessarily due to an inability to pay dividends.
Instead, it reflects a strategic decision by the company to prioritize long-term growth and value creation over immediate dividend payouts. Investors should consider their individual investment goals and risk tolerance when evaluating such companies.
On the other hand, mature companies with limited growth prospects might prioritize returning profits to shareholders, resulting in higher dividend cover ratios. These companies are often seen as more attractive to income-driven investors who seek regular dividend payouts.
Recognizing the strategic use of dividend cover is also part of a broader understanding of corporate governance and financial strategy. It underscores the need for investors to discern between different corporate strategies and how these strategies can impact dividend policies.
Conclusion
Understanding dividend cover is essential for investors who aim to evaluate the risks associated with a company’s dividend payments. While a higher dividend cover ratio serves as a positive indicator for sustainable and possibly increasing dividend payouts, lower ratios necessitate a more thorough investigation into a company’s financial health and strategic direction.
Being informed about dividend cover enriches an investor’s ability to understand a company’s financial posture relative to its distribution policy. This knowledge empowers investors to align their investment strategies with their financial goals, whether they are seeking growth, stability, or income.
For further exploration into dividend cover and related financial metrics, investors are encouraged to refer to reputable financial education websites that offer more comprehensive discussions on these topics, helping them to refine their understanding and application of these important financial metrics.
- Written by: admin
- Category: Uncategorized
- Published: September 19, 2026
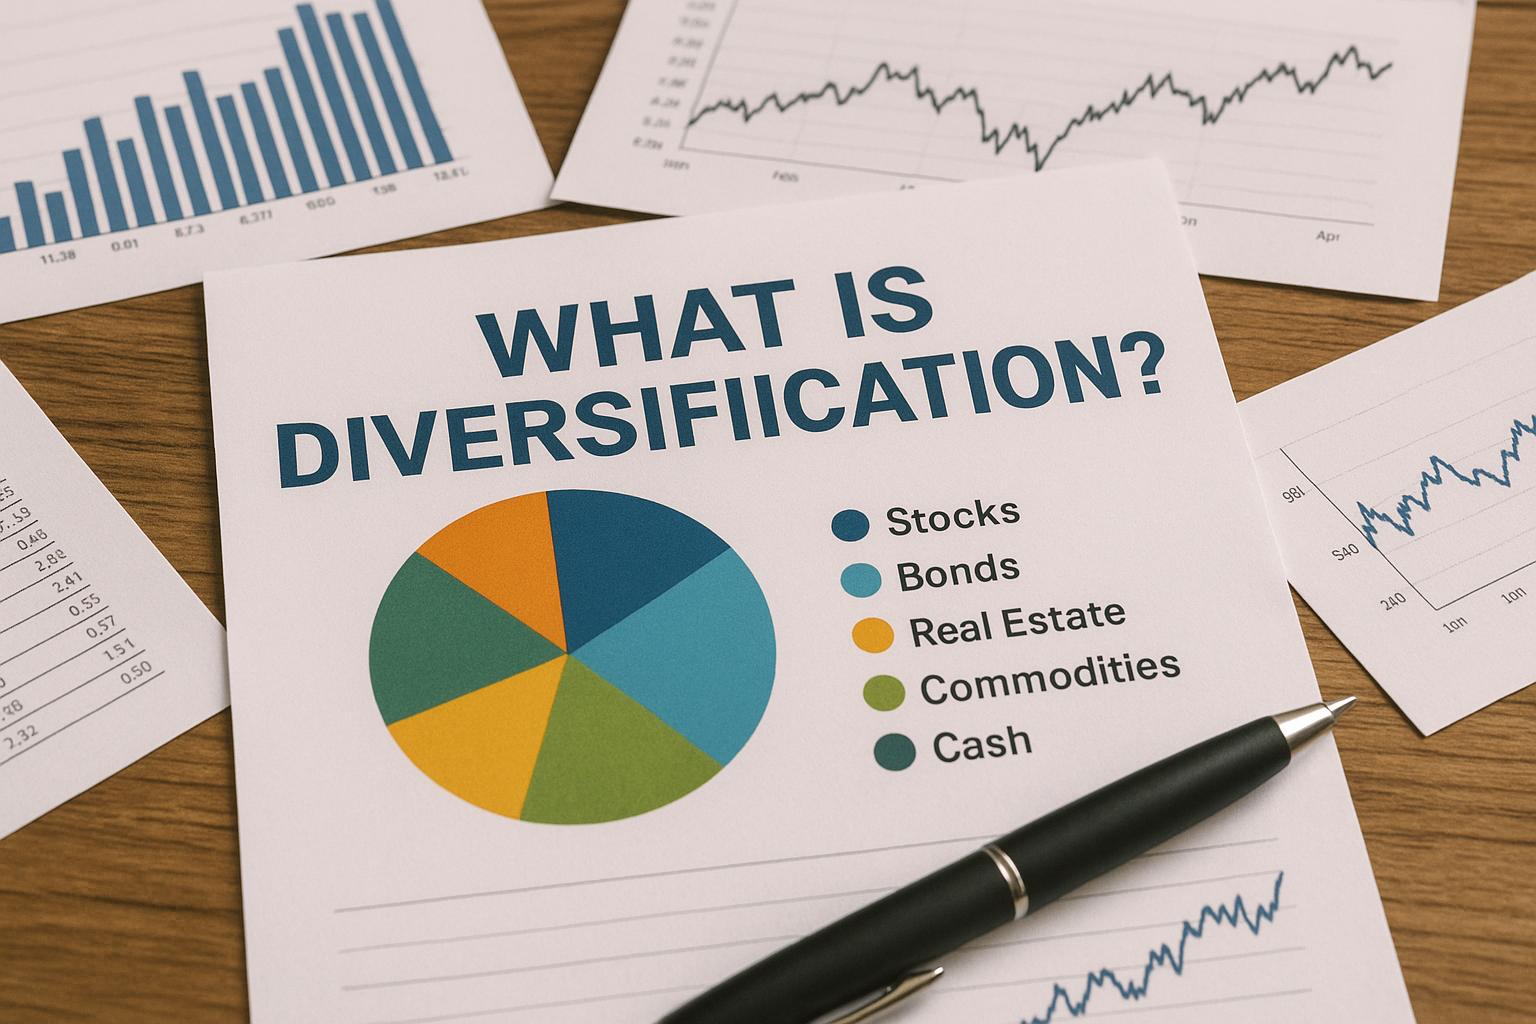
Understanding Diversification
Financial Diversification
Benefits of Financial Diversification
Business Diversification
Types of Business Diversification
Conclusion
- Written by: admin
- Category: Uncategorized
- Published: September 12, 2026

Understanding Share Dilution
Share dilution is a critical concept in corporate finance that occurs when a company issues additional shares, thus reducing the ownership percentage of existing shareholders. This action has significant implications for the market value of individual shares, as well as for the overall structure of shareholder ownership within a company.
How Does Dilution Happen?
Companies resort to issuing more shares for various strategic reasons. One of the most common motivations is the need to raise additional capital. By introducing more shares into the market, a company can attract investors who provide the financial resources needed to support the organization’s growth ambitions. These funds might be used to develop new projects, expand operations, or enter new markets. Furthermore, dilution can occur when firms decide to acquire other businesses, using stock as currency for the transaction. This method allows companies to conserve cash while expanding their reach or entering new areas of operation.
Another scenario in which dilution might occur is through employee compensation. Many companies use stock options as part of their remuneration packages to attract, retain, and incentivize employees, offering them a stake in the company’s future success. However, issuing shares for these stock options also increases the total number of shares outstanding, thereby diluting the ownership stakes of existing shareholders.
Effects on Share Value
The process of issuing new shares has a direct impact on share value. When the same profits and assets that the company had backing its initial shares are spread over a larger number of shares, the earnings per share (EPS) may decrease. EPS is a crucial metric that investors use to gauge a company’s profitability, and a reduction in EPS could suggest that each share represents a smaller portion of the company’s net income.
A decrease in EPS might lead to a drop in the stock’s market value as investors reevaluate the company’s profitability prospects. Nevertheless, the actual impact of dilution can depend significantly on the reasons behind the new issuance and the market’s perception of the company’s potential for future growth induced by the additional capital. If the reason for issuing new shares is achieved successfully, such as a lucrative acquisition or a profitable new project, investors might view the dilution as beneficial in the long run.
Implications for Shareholders
For shareholders, dilution has direct implications by decreasing their percentage of ownership in the company. This decrease in ownership percentage can translate into reduced voting power at shareholder meetings, as voting rights are often based on the number of shares owned. Consequently, shareholders might have less influence over corporate decisions.
Despite its often-negative connotation, dilution is not inherently detrimental. If the capital raised through additional shares allows the company to pursue strategies that lead to substantial growth or increased profitability, shareholders could benefit from a higher share price in the future. In such cases, the initial negative impact of dilution may be offset by improved financial performance, enhancing the overall value of a shareholder’s investment.
Preventing or Mitigating Dilution
Companies seeking to mitigate the negative effects of share dilution on existing shareholders may offer anti-dilution provisions. These provisions are designed to protect shareholders from losing their ownership percentage and can take a variety of forms.
One common mechanism is the right of first refusal, which allows existing shareholders to purchase additional shares at a discounted price before new investors are offered shares. This ensures that current shareholders have the opportunity to maintain their proportional ownership in the company by acquiring additional shares at a favorable rate.
Another approach is through the adjustment of conversion rates for convertible securities. Convertible securities, such as convertible bonds or preferred shares, can be converted into common stock at a given rate. Companies might adjust these conversion rates favorably for existing shareholders to help maintain their ownership stakes.
By implementing such strategies, businesses aim to preserve shareholder confidence and ensure that their shares remain attractive to both current and potential investors.
Broader Perspectives on Share Dilution
To delve deeper into the nuances of share dilution, it may be beneficial to explore industry-specific financial websites or platforms that provide insights into stock market dynamics, shareholder rights, and corporate finance strategies. Understanding the broader economic context and trends within specific industries can offer valuable perspectives on how dilution might affect the value of shares and the overall financial health of a company.
In conclusion, share dilution is an important dynamic to consider in the realm of corporate finance and investing. While it involves expanding the number of shares and potentially reducing the equity held by current shareholders, the long-term effects can vary depending on the underlying strategies and objectives that prompt the issuance of additional shares. Existing and potential investors must be cognizant of both the potential challenges and opportunities that share dilution may present to make informed investment decisions.
- Written by: admin
- Category: Uncategorized
- Published: September 5, 2026
In accounting and finance, understanding how to properly manage and report asset depreciation is essential for any business. This knowledge not only ensures compliance with legal and financial reporting requirements but also provides managers and stakeholders with accurate insights into a company’s financial health. By spreading an asset’s purchase cost over its useful life, businesses can reflect a more realistic asset valuation on their financial records and can make informed decisions about future investments and resource allocation.
Understanding Depreciation
Depreciation is an accounting method used for allocating the cost of a tangible asset over its useful life. This approach helps businesses account for the reduction in value of an asset as it ages and is utilized over time. It is crucial for financial planning as it provides a mechanism for businesses to recover part of the asset’s cost and reflects the wear and tear, as well as obsolescence due to technological advancements, that decrease an asset’s utility and value.
Why Depreciation Matters
The importance of depreciation in financial management can be understood from multiple perspectives:
1. Asset Valuation: Depreciation offers a systematic way of reducing the recorded cost of the asset, reflecting its current value on the balance sheet as it gets older and possibly less productive.
2. Expense and Revenue Matching: By matching the depreciation expense with the revenues that the asset helps generate, businesses can get a more accurate picture of their profitability. This matching principle is a fundamental aspect of accrual accounting.
3. Tax Implications: Depreciation can significantly influence a company’s taxable income. Claiming depreciation expenses as deductions can lower taxable income, thereby reducing the overall tax liability.
Methods of Depreciation
Choosing the appropriate method of depreciation is crucial as it can impact financial results and tax obligations. Here’s a closer look at the different methods:
Straight-Line Method:
This is the simplest and most commonly used method. It divides the asset’s cost evenly across its useful life span. The formula applied is:
(Initial Cost – Salvage Value) / Useful Life in Years.
Declining Balance Method:
This is an accelerated depreciation method that applies a higher depreciation rate earlier in the asset’s life, which gradually declines over time. It is suitable for assets that rapidly lose their value.
Units of Production Method:
This method allocates depreciation based on actual usage or output, making it ideal for machinery and vehicles. Depreciation is high when the output level is high, and it tapers off when the asset is less used.
Sum-of-the-Years-Digits Method:
This approach also allocates more depreciation in the early years of an asset’s life and less in later years. It uses a decreasing fraction to calculate depreciation, ensuring that older assets reflect less depreciation.
Factors Influencing Depreciation
Several key factors affect how depreciation is calculated and reported:
Initial Cost: This includes the purchase price of the asset and any other expenses necessary to prepare the asset for use, such as installation and transportation fees.
Useful Life: An estimate of how long the asset will be productive within the business. This estimation can be influenced by factors such as industry standards, technological changes, and asset usage patterns.
Salvage Value: The anticipated value of the asset at the end of its useful life. This is what the business expects to recover when the asset is sold or disposed of.
Depreciation Rate: The rate at which an asset’s value is depreciated. This rate varies depending on the chosen method of depreciation and can significantly impact financial reporting and tax calculations.
Depreciation in Financial Statements
Depreciation has a marked effect on various financial statements, providing insights into asset value, revenue, expenses, and overall financial health:
On the balance sheet, depreciation affects the book value of assets. By allocating a portion of the asset’s cost as an expense, the value of tangible assets is adjusted, reflecting their diminishing utility over time.
In the income statement, depreciation is recorded as an expense, which reduces net income. As a non-cash expense, it represents neither inflows nor outflows of cash but impacts profitability by aligning costs with the generated revenues.
Even though depreciation doesn’t impact cash flow directly by reducing net income, it can influence tax obligations and subsequent cash flow, given that the resulting lower taxable income often results in reduced taxes.
For businesses navigating the complexities of accounting and finance, understanding depreciation is vital. It ensures capital investments are accurately represented on financial records, which in turn supports strategic financial planning, operational decision-making, and regulatory compliance.
For more detailed information and expert guidance on accounting and finance topics, consider resources such as Investopedia or consult with a certified accountant. A comprehensive understanding of how depreciation works is crucial for sound financial reporting and planning, ensuring that a business’s finances accurately mirror its operational realities.
- Written by: admin
- Category: Uncategorized
- Published: August 29, 2026
Understanding Debt Financing
Debt financing is an essential way for businesses to secure funds and propel their growth. It involves borrowing money from external sources and carries an obligation for the borrower—typically a company—to repay the borrowed amount along with any applicable interest over a designated timeframe.
The Basics of Debt Financing
When a company decision-makers opt for debt financing, they are agreeing to the terms laid down by the lender. These lenders can range from traditional banks to individual investors, and even diverse financial institutions like credit unions or fintech companies. The terms of these agreements are critical as they include significant details such as the repayment schedule, interest rate, and specific covenants or conditions that must be maintained throughout the loan tenure. These terms form the backbone of the debt financing structure and dictate the borrowing company’s financial commitments over the period of the loan.
Advantages of Debt Financing
A major advantage of opting for debt financing is that it enables companies to maintain ownership and control over their operations. Unlike equity financing, which requires surrendering a portion of ownership or shares, debt simply requires repayment of the borrowed sum plus interest, leaving the ownership structure unchanged. This is particularly beneficial for businesses that are careful about diluting their ownership. Additionally, the interest payments made on the debt can often be considered tax-deductible business expenses, providing a potential financial advantage. This tax shield can mitigate the overall cost of debt, making it a financially appealing option for many companies looking to optimize their tax obligations.
Disadvantages of Debt Financing
On the other hand, debt financing is not without its drawbacks. A fundamental challenge is that it imposes mandatory, regular repayment requirements which can exert pressure on the company’s cash flow. In instances where the business experiences financial headwinds, these fixed repayment obligations can strain its fiscal stability. Furthermore, high debt levels can be risky because the obligation to repay these debts exists independently of the company’s financial performance. Under adverse economic or business conditions, this can lead to financial distress or even insolvency if the company is unable to meet its debt obligations.
Types of Debt
Debt instruments are varied, each possessing unique characteristics that make them suited for different financing needs. Understanding these types is crucial in crafting a tailored financing strategy:
* Bonds: These are long-term debt securities that are typically traded in financial markets. Bonds are a prevalent choice for companies seeking significant amounts of capital and willing to pay back over an extended period, often ranging from 5 to 30 years.
* Loans: These involve sums of money lent by financial institutions like banks or credit unions under agreed-upon terms. They can vary widely in size and duration, from short-term financial needs to comprehensive long-term financing strategies.
* Notes: Unlike bonds and general loans, notes are typically short-term debt instruments. They necessitate repayment within shorter durations and can frequently cater to immediate financing needs.
Debt Financing vs. Equity Financing
The decision between debt and equity financing can be pivotal for a company’s financial strategy. Equity financing entails raising capital through the sale of company shares, which results in the dilution of ownership. However, it liberates the company from the burden of fixed repayments that debt financing entails. The choice between the options requires a rigorous evaluation of the costs, benefits, and potential impact on the company’s operational autonomy. Companies must weigh the financial implications, both short-term and long-term, based on their strategic goals and financial health to make informed decisions.
Conclusion
Debt financing remains a fundamental avenue for companies that seek funding without relinquishing ownership. Nonetheless, it embodies specific risks associated with regular repayment commitments and potential financial strain during downturns. Considering the complexity and strategic impact, companies must approach debt financing with caution and thorough analysis. Understanding the nuances and aligning them with the company’s objectives is crucial. For a deeper dive into debt financing strategies, businesses are encouraged to seek further resources or consultations with financial experts. Many comprehensive guides are available online. One such reliable resource is Investopedia, which can provide additional insights and guidance, ensuring more informed decision-making tailored to the distinct needs of businesses aiming to leverage debt as a financial instrument.
- Written by: admin
- Category: Uncategorized
- Published: August 25, 2026
Understanding Custody in Investing
In the realm of investing, custody refers to the safekeeping of an investor’s securities and financial assets. This practice involves holding and protecting investment assets on behalf of clients, ensuring their safety and the precise recording of transactions. Typically, custody services are offered by specialized institutions known as custodians.
Role of Custodians
Custodians are financial institutions responsible for the management and safeguarding of a client’s investments. These institutions are generally banks or specialized financial firms, whose primary function is to securely hold the securities, whether stocks, bonds, or other assets, in electronic or physical form, ensuring that they are secure and properly accounted for.
Functions of Custodians
While custodians are mainly tasked with the safekeeping of assets, they perform a broad range of important functions that are crucial for investors.
Trade Settlement: Custodians facilitate the settlement of trades executed by fund managers or individual investors, ensuring that the transfer of ownership of securities is accurately recorded and processed. This involves coordinating with various market participants to finalize trades accurately.
Income Collection: They take on the responsibility of collecting and managing income generated from investments, such as dividends from stocks or interest from bond holdings. This involves timely distribution and accurate record-keeping of all income streams.
Corporate Actions: Custodians manage corporate events such as stock splits, mergers, or rights issues, ensuring that the interests of clients are handled efficiently. They oversee these activities to ensure that investors receive their entitlements without unnecessary delays or errors.
Reporting: Detailed reports on the holdings and transactions are provided by custodians, granting investors insights into their portfolio’s performance and current status. These reports assist investors in making informed decisions regarding their investment strategies.
Furthermore, custodians are involved in facilitating proxy voting, a process where investors can vote on corporate matters even if they do not attend meetings in person. They ensure that the votes are cast according to the investor’s instructions. This is particularly relevant for shareholders interested in maintaining influence over the companies in which they hold stakes.
Why Investors Need Custody Services
Custody services are essential for protecting investors’ assets from loss, theft, or fraud. Holding assets through a custodian mitigates these risks significantly. By outsourcing the responsibility for safeguarding and administrative tasks associated with large portfolios, investors can focus on strategy and growth more effectively.
Custodians provide an essential layer of transparency and accountability, offering investors meticulous record-keeping and ensuring compliance with both domestic and international regulatory requirements. This is especially important for institutional investors who manage significant sums of money on behalf of clients or shareholders. The regulatory environment is continuously evolving, and custodians keep abreast of legal obligations, thus shielding investors from potential legal and financial repercussions.
Moreover, in the context of global investment portfolios, custodians play a crucial role by dealing with different jurisdictions and ensuring compliance with various local regulations. They enable investors to access diverse markets, widening opportunities for investment while reducing the complexity involved in navigating international regulations and logistics.
Custody services also assist investors in ensuring that their portfolios are aligned with their risk tolerance and investment goals. Custodians are often able to provide customized services geared to specific investment strategies or regulatory statuses, such as tax-advantaged accounts or ESG (Environmental, Social, and Governance)-focused investments.
Conclusion
Understanding the concept of custody in investing is indispensable for any investor aiming to safeguard their assets effectively. As financial markets continue to evolve and become increasingly complex, the role of custodians remains paramount. They offer not only security and efficiency but also a streamlined and strategic approach to managing investments.
Custodians serve as critical components in the broader financial system, which relies on their services to operate efficiently and transparently. Their ongoing innovation and adaptation to new technological advancements ensure that both individual and institutional investors have the tools necessary to maintain and grow their investments in a secure manner.
For a more in-depth exploration of financial concepts and the evolving role of custodians, potential investors are encouraged to consult reliable financial resources and consider exploring further in reputable financial platforms. These resources can provide valuable insights and detailed analyses that can equip investors with the knowledge necessary to make informed decisions in an ever-changing economic landscape.
- Written by: admin
- Category: Uncategorized
- Published: August 15, 2026
Understanding the Current Account in Finance
In the intricate world of international finance, the current account stands as a pivotal component of a country’s balance of payments, illustrating economic transactions between a nation and its global counterparts over a specified timeframe. This account is tailor-made to assess the net flow of goods, services, income, and current transfers, offering insight into the financial health and economic activities of a country.
Components of the Current Account
When delving into the current account, one discovers the multiple elements that it comprises. These elements are vital in calculating the balance and capturing the various financial interactions between countries.
Goods and Services
The record of goods and services forms the backbone of the current account. Here, all forms of imports and exports are meticulously noted. When a nation engages in export activities, it welcomes foreign currency inflows. In contrast, when importing, it results in a currency outflow. An economy boasting a positive balance in this section has more exports than imports, often termed a trade surplus. Conversely, a negative balance implies a deficit, where imports surpass the expansive limits of exports. This fundamental component serves as an indicator of a country’s trade health, influences exchange rates, and dictates monetary policies.
Income
The income component of the current account encompasses earnings derived from foreign investments and wages attained globally by domestic residents. It spans:
- Primary Income: This includes revenues from direct investments and portfolio investments along with compensation offered to employees working internationally. These are generally derived from tangible investments and financial assets abroad.
- Secondary Income: This involves one-way transfers, unaccompanied by reciprocation of goods or services. Examples include foreign aid, personal remittances sent by expatriates, and other transfers that don’t yield an exchange.
Current Transfers
The third vital segment, Current Transfers, involves unilateral transactions, meaning the transfer of money, goods, or services occurs without receiving anything in return. This category accommodates foreign aid, charitable donations, or personal gifts transacted across countries. They are indicative of the remittance practices of a country and serve as social and economical connections between foreign nationals and their home countries.
Significance of the Current Account Balance
The balance represented in the current account symbolizes more than mere arithmetic— it portrays the economic vigor and stability of a nation. A surplus current account designates that a country is effectively a global creditor, channeling more funds into the world than it borrows. Alternatively, a deficit suggests dependency on foreign capital, reflecting borrowing patterns. Countries sustaining persistent deficits might encounter scrutiny regarding their debt management and might face fluctuations in their credit ratings. These imbalances could necessitate economic policy adjustments or reforms to ensure long-term sustainability.
Current Account vs. Capital Account
It’s crucial not to misinterpret the current account as synonymous with the capital account, even though both are facets of the balance of payments. While the current account extensively deals with trade, income, and transfers, the capital account is concerned with financial transactions like capital transfers, investments, and long-term borrowing or lending. Understanding the entwined relation between these accounts is essential when analyzing the full scope of a nation’s financial dealings with the rest of the world, as they collectively map out the economic interaction balance.
Analyzing Trends and Implications
Analyzing the trends encapsulated within the current account offers insights into profound economic policies, competitiveness, and trade relations of a country. Economists and analysts delve into these trends to forecast economic pathways, gauge financial stability, and re-evaluate trade agreements. Observations, found through scrutiny of the current account balance, often lead to recommendations for policy modifications that can help in navigating future economic challenges. For further enrichment, institutions like the International Monetary Fund (IMF) provide expansive resources and informed literature for comprehensive understanding.
Concluding Thoughts
In conclusion, the current account is intrinsic to understanding a country’s economic dynamics and international economic interactions. By revealing the picture of a nation’s global financial activities—exports, imports, foreign income, and unilateral transfers—the current account acts as an economic barometer. It is reflective of economic viability, influencing policy formulations, and defining trade strategies. Thus, it is a high-value indicator used to forecast and shape the economic strategies of a nation amidst the global market network. The study of the current account is indispensable for economists and policymakers aiming to optimize a country’s economic standing in the ever-evolving global economic landscape.
- Written by: admin
- Category: Uncategorized
- Published: August 8, 2026
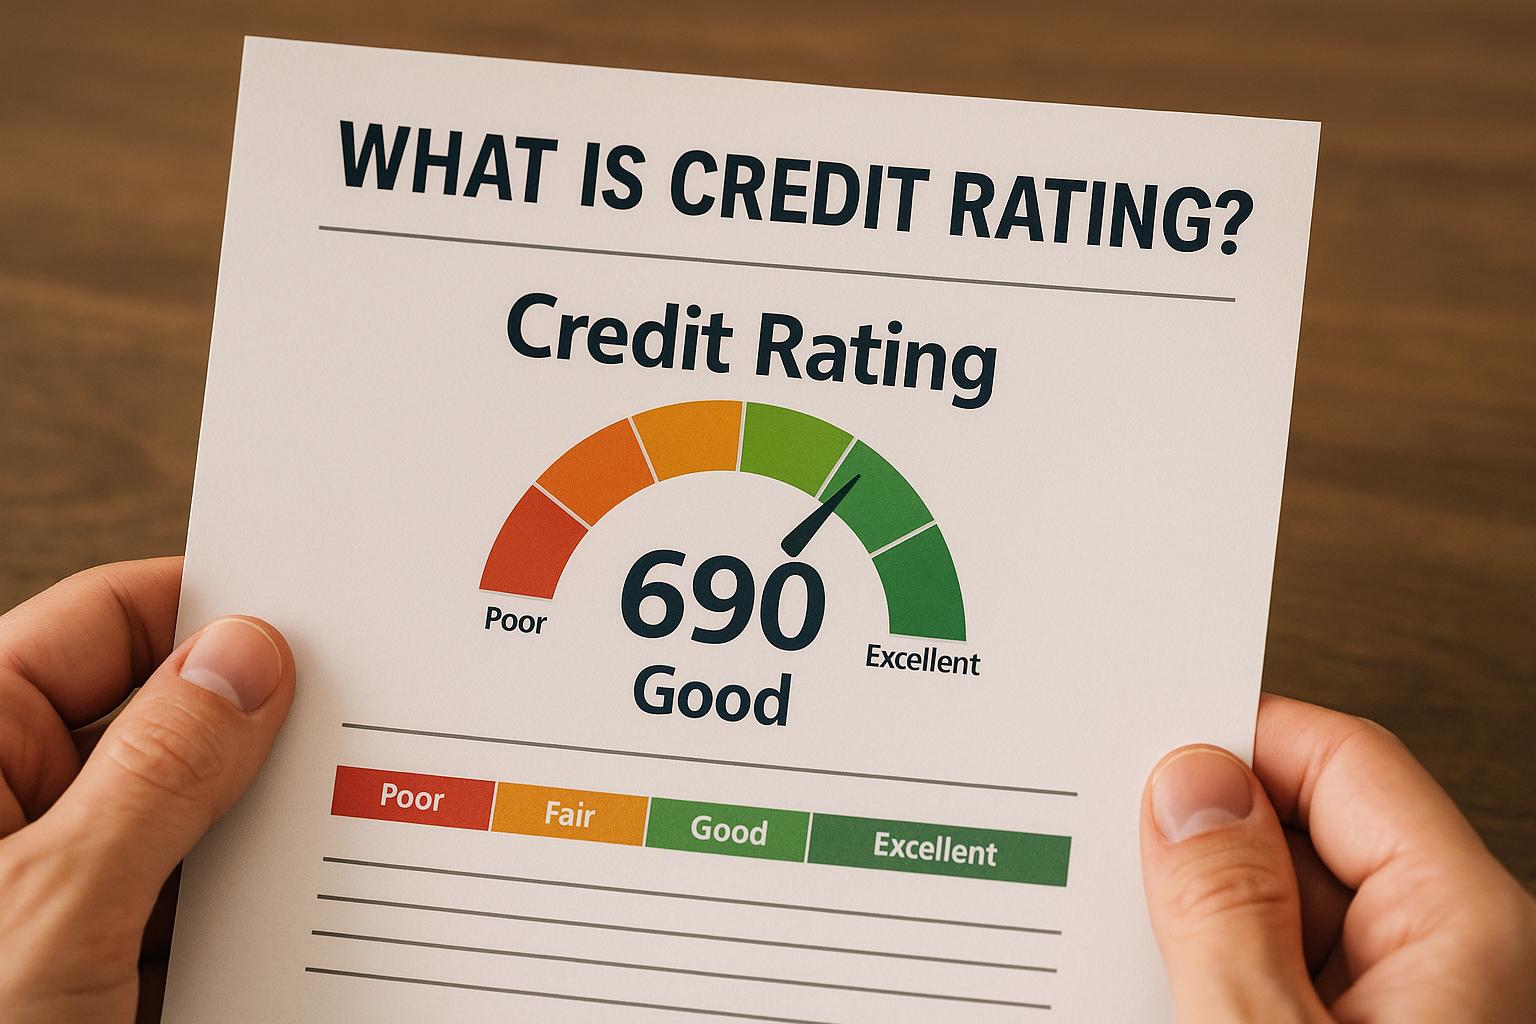
Understanding Credit Ratings
A credit rating is a quantified assessment of the creditworthiness of a borrower, which can be an individual, corporation, or a sovereign nation. These ratings serve as essential tools for investors and financial institutions, helping them gauge the likelihood that a borrower will default on their debt obligations.
The Role of Credit Rating Agencies
Credit rating agencies are indispensable players in the financial markets. Their primary function is to provide independent evaluations of the credit risk associated with borrowers. Moody’s, Standard & Poor’s (S&P), and Fitch Ratings are some of the most prominent agencies in this field. They apply a variety of methodologies to assess and assign credit ratings. Such ratings typically range from high-grade, which indicates low credit risk, to speculative or junk, which suggests a higher credit risk.
Functions of Credit Rating Agencies
Credit rating agencies perform comprehensive analyses of financial health, economic conditions, and market trends. Through rigorous methodologies, they assess factors like an entity’s financial statements, debt levels, cash flow, and market position. These agencies serve as an intermediary between borrowers and investors, translating complex financial data into accessible, standardized ratings. By doing so, they contribute substantially to transparency and efficiency in the financial markets.
Why Credit Ratings Matter
Credit ratings hold significant importance due to a variety of factors:
Investor Confidence: Investors heavily depend on credit ratings to comprehend the risks and potential returns associated with different investment prospects. A favorable credit rating can enhance the investor’s confidence in the borrower’s ability to meet financial obligations.
Borrowing Costs: The credit rating assigned to a borrower can profoundly influence the interest rates they must pay. Generally, a higher credit rating is synonymous with lower borrowing costs. This is because lenders perceive higher-rated borrowers as lower risk, leading to cheaper access to credit.
Market Access: Entities with superior credit ratings enjoy enhanced access to capital markets. This facilitates easier and more cost-effective fundraising. Companies and governments with strong credit ratings can issue bonds and other types of debt with relative ease, attracting a broader range of investors.
The Rating Scale
The credit rating scale utilized by credit rating agencies often ranges from AAA or Aaa, signifying the highest credit quality, to D, indicating default. For instance, Standard & Poor’s employs a scale that comprises categories such as AAA, AA, A, BBB, BB, and below. Each category reflects distinct levels of credit risk, offering investors a clear gauge of the borrower’s financial stability and the likelihood of default.
Characteristics of the Rating Scale
The rating scale is methodically structured and hierarchical in nature. It organizes various degrees of credit risks in a manner that aids investors in making crucial decisions. The scale is generally broken down into investment-grade ratings and speculative-grade ratings. Investment-grade ratings (AAA to BBB) are indicative of lower default risk, whereas speculative-grade ratings (BB and lower) suggest higher risk and potential default.
Limitations of Credit Ratings
While credit ratings provide invaluable insights, they are not without their limitations. It is crucial for investors to be aware of these constraints when evaluating risk:
Subjectivity: The processes and methodologies used by credit rating agencies inherently involve subjective judgments. Different agencies might offer different ratings for the same borrower, leading to discrepancies that could impact investment decisions.
Timeliness: Ratings are not always updated promptly to reflect new financial conditions or market developments. Consequently, investors may occasionally rely on outdated information, affecting their risk assessment and decision-making processes.
Potential Conflicts of Interest: Given that rating agencies are typically compensated by the entities they rate, potential conflicts of interest may arise. This relationship may compromise the objectivity of the ratings, raising concerns about the impartiality of the evaluations provided.
The Evolving Landscape of Credit Ratings
The landscape of credit ratings is continuously evolving. Rating agencies are increasingly adopting technological advances and data analytics tools to refine their methodologies and improve the accuracy of the ratings. The use of machine learning and algorithmic tools is becoming prevalent, which could enhance predictive capabilities and minimize subjectivity.
In conclusion, credit ratings serve as crucial instruments in assessing credit risk. Despite their limitations, they continue to play an influential role in shaping investment strategies and financial decisions across global markets. For those interested in delving deeper into credit ratings and their implications, exploring resources from financial institutions can provide additional insights and tools.
Recent Comments