Archives: What is dividend cover?
Understanding Dividend Cover
Dividend cover is a crucial financial metric used by investors and analysts to evaluate the sustainability of a company’s dividend payments. Essentially, it provides valuable insight into a company’s ability to comfortably pay its dividends from its net earnings. Understanding this metric can assist investors in making informed decisions regarding their investment portfolios.
Definition and Calculation
Dividend cover is determined by dividing a company’s net earnings by the dividends that are paid to its shareholders. The formula for this calculation is presented as follows:
Dividend Cover = Net Income / Dividends Declared
By applying this formula, the ratio obtained reveals the number of times a company can afford to pay its current level of dividends using its net income. A higher dividend cover ratio typically suggests that a company is well-positioned to maintain or even increase its dividends. In contrast, a lower ratio can raise concerns about the long-term sustainability of the company’s dividend payouts.
The dividend cover ratio is an important measure for assessing a company’s financial health. It reflects a company’s earnings relative to its dividend obligations, offering a clear picture of whether the company can sustain its dividend policy without risking its financial stability. A key point to remember is that a balance between earnings and dividend payments is critical to safeguarding a company’s financial health.
Interpreting Dividend Cover
It is generally considered that a dividend cover ratio of 2 or more is indicative of a healthy financial state. This suggests that the company’s earnings are at least twice the amount it pays in dividends. Such a scenario signals that the company generates adequate earnings to cover its dividend payouts comfortably.
Conversely, a ratio of less than 1 might suggest a potential risk, indicating that a company is distributing more money in dividends than it actually earns. This situation is not sustainable in the long term unless the company has substantial reserves or resorts to taking on debt. For investors seeking reliable dividend income, a low dividend cover ratio can thus serve as a warning sign.
An important aspect to consider is the volatility of earnings. Even if a company has a strong dividend cover at present, fluctuating earnings can alter this metric considerably. Therefore, it is essential to consider not only the current ratio but also the underlying trends in earnings and how they may impact the dividend cover in the future.
Why Dividend Cover Matters
For investors, the dividend cover ratio is a pivotal metric when considering the potential growth or maintenance of a company’s dividend over time. A strong dividend cover ratio can be an indication of a company’s financial stability and its ability to generate consistent earnings. Consequently, such companies may be attractive choices for investors focused on generating income from their investments.
In stark contrast, companies with a low dividend cover are often vulnerable, as they might struggle to maintain their dividend payouts during periods of declining profits or adverse economic conditions. When faced with such circumstances, companies with insufficient dividend cover may resort to cutting their dividends, potentially leading to negative investor sentiment and a decrease in share price.
Evaluating the dividend cover ratio is, therefore, a part of an investor’s comprehensive assessment process. It is not only about understanding a company’s current financial status but also gaining foresight into its financial capability to reward shareholders in the future. A robust dividend cover is often reflective of good financial management and operational efficiency.
Dividends and Company Strategy
There is considerable diversity among companies in terms of how they manage their dividend cover, influenced heavily by their unique investment strategies. For instance, companies experiencing growth might prefer to reinvest their earnings to harness growth opportunities rather than distributing them to shareholders in the form of dividends. This strategic choice might lead to a lower dividend cover ratio, but it is not necessarily due to an inability to pay dividends.
Instead, it reflects a strategic decision by the company to prioritize long-term growth and value creation over immediate dividend payouts. Investors should consider their individual investment goals and risk tolerance when evaluating such companies.
On the other hand, mature companies with limited growth prospects might prioritize returning profits to shareholders, resulting in higher dividend cover ratios. These companies are often seen as more attractive to income-driven investors who seek regular dividend payouts.
Recognizing the strategic use of dividend cover is also part of a broader understanding of corporate governance and financial strategy. It underscores the need for investors to discern between different corporate strategies and how these strategies can impact dividend policies.
Conclusion
Understanding dividend cover is essential for investors who aim to evaluate the risks associated with a company’s dividend payments. While a higher dividend cover ratio serves as a positive indicator for sustainable and possibly increasing dividend payouts, lower ratios necessitate a more thorough investigation into a company’s financial health and strategic direction.
Being informed about dividend cover enriches an investor’s ability to understand a company’s financial posture relative to its distribution policy. This knowledge empowers investors to align their investment strategies with their financial goals, whether they are seeking growth, stability, or income.
For further exploration into dividend cover and related financial metrics, investors are encouraged to refer to reputable financial education websites that offer more comprehensive discussions on these topics, helping them to refine their understanding and application of these important financial metrics.
Archives: What is diversification?
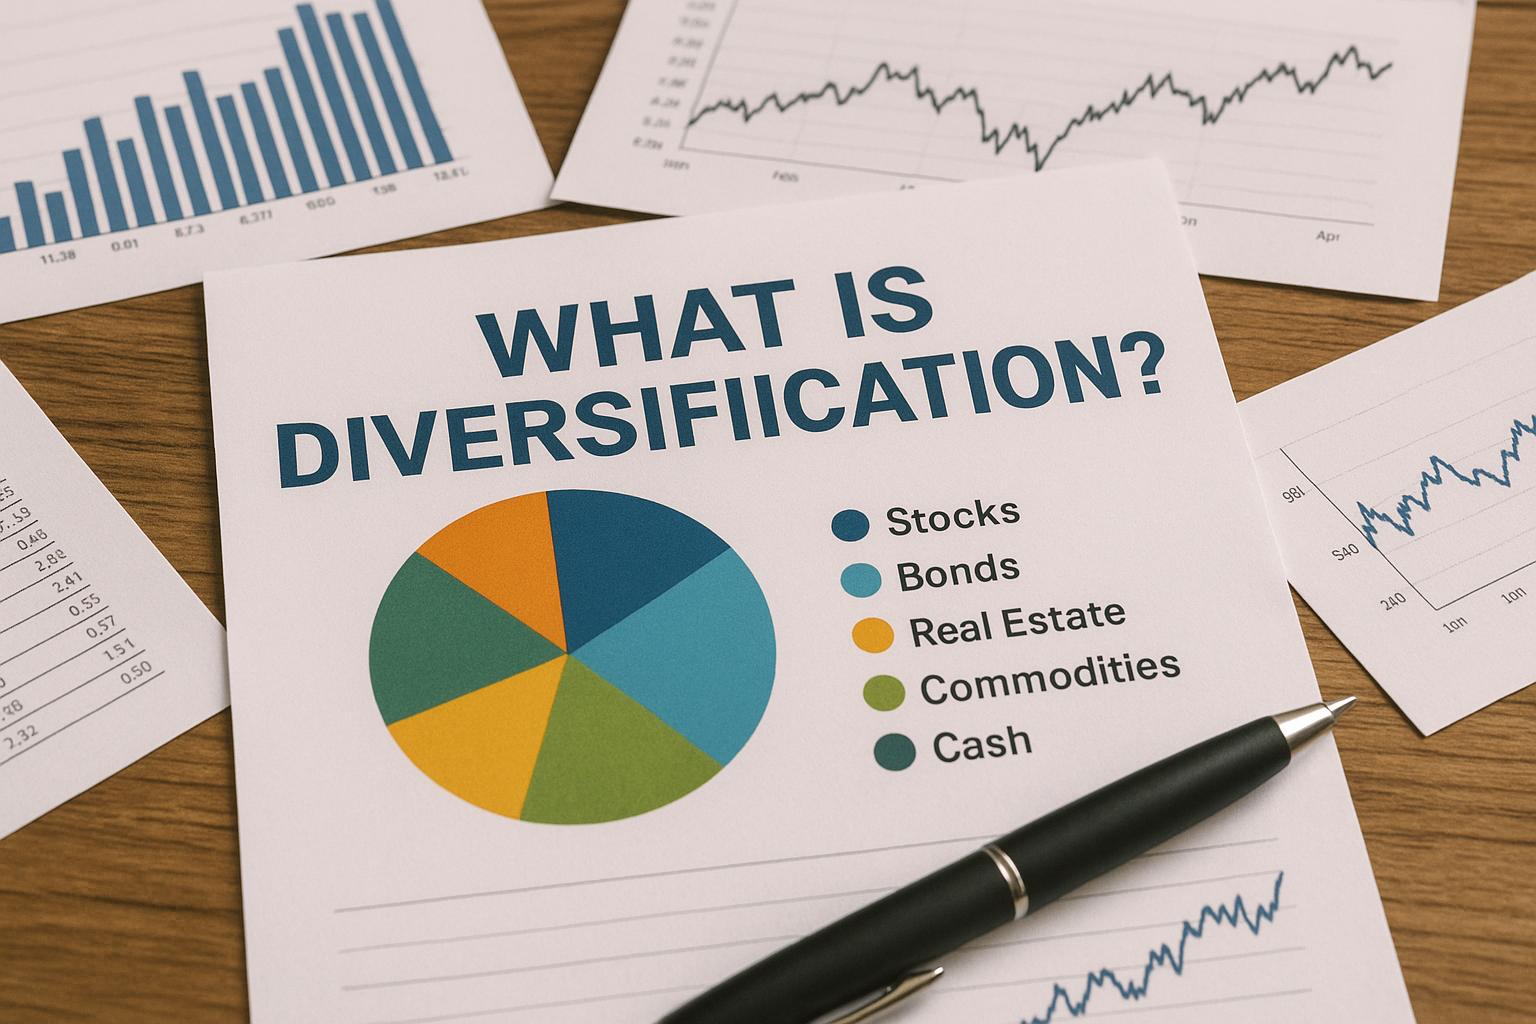
Understanding Diversification
Financial Diversification
Benefits of Financial Diversification
Business Diversification
Types of Business Diversification
Conclusion
Archives: What is dilution in shares?

Understanding Share Dilution
Share dilution is a critical concept in corporate finance that occurs when a company issues additional shares, thus reducing the ownership percentage of existing shareholders. This action has significant implications for the market value of individual shares, as well as for the overall structure of shareholder ownership within a company.
How Does Dilution Happen?
Companies resort to issuing more shares for various strategic reasons. One of the most common motivations is the need to raise additional capital. By introducing more shares into the market, a company can attract investors who provide the financial resources needed to support the organization’s growth ambitions. These funds might be used to develop new projects, expand operations, or enter new markets. Furthermore, dilution can occur when firms decide to acquire other businesses, using stock as currency for the transaction. This method allows companies to conserve cash while expanding their reach or entering new areas of operation.
Another scenario in which dilution might occur is through employee compensation. Many companies use stock options as part of their remuneration packages to attract, retain, and incentivize employees, offering them a stake in the company’s future success. However, issuing shares for these stock options also increases the total number of shares outstanding, thereby diluting the ownership stakes of existing shareholders.
Effects on Share Value
The process of issuing new shares has a direct impact on share value. When the same profits and assets that the company had backing its initial shares are spread over a larger number of shares, the earnings per share (EPS) may decrease. EPS is a crucial metric that investors use to gauge a company’s profitability, and a reduction in EPS could suggest that each share represents a smaller portion of the company’s net income.
A decrease in EPS might lead to a drop in the stock’s market value as investors reevaluate the company’s profitability prospects. Nevertheless, the actual impact of dilution can depend significantly on the reasons behind the new issuance and the market’s perception of the company’s potential for future growth induced by the additional capital. If the reason for issuing new shares is achieved successfully, such as a lucrative acquisition or a profitable new project, investors might view the dilution as beneficial in the long run.
Implications for Shareholders
For shareholders, dilution has direct implications by decreasing their percentage of ownership in the company. This decrease in ownership percentage can translate into reduced voting power at shareholder meetings, as voting rights are often based on the number of shares owned. Consequently, shareholders might have less influence over corporate decisions.
Despite its often-negative connotation, dilution is not inherently detrimental. If the capital raised through additional shares allows the company to pursue strategies that lead to substantial growth or increased profitability, shareholders could benefit from a higher share price in the future. In such cases, the initial negative impact of dilution may be offset by improved financial performance, enhancing the overall value of a shareholder’s investment.
Preventing or Mitigating Dilution
Companies seeking to mitigate the negative effects of share dilution on existing shareholders may offer anti-dilution provisions. These provisions are designed to protect shareholders from losing their ownership percentage and can take a variety of forms.
One common mechanism is the right of first refusal, which allows existing shareholders to purchase additional shares at a discounted price before new investors are offered shares. This ensures that current shareholders have the opportunity to maintain their proportional ownership in the company by acquiring additional shares at a favorable rate.
Another approach is through the adjustment of conversion rates for convertible securities. Convertible securities, such as convertible bonds or preferred shares, can be converted into common stock at a given rate. Companies might adjust these conversion rates favorably for existing shareholders to help maintain their ownership stakes.
By implementing such strategies, businesses aim to preserve shareholder confidence and ensure that their shares remain attractive to both current and potential investors.
Broader Perspectives on Share Dilution
To delve deeper into the nuances of share dilution, it may be beneficial to explore industry-specific financial websites or platforms that provide insights into stock market dynamics, shareholder rights, and corporate finance strategies. Understanding the broader economic context and trends within specific industries can offer valuable perspectives on how dilution might affect the value of shares and the overall financial health of a company.
In conclusion, share dilution is an important dynamic to consider in the realm of corporate finance and investing. While it involves expanding the number of shares and potentially reducing the equity held by current shareholders, the long-term effects can vary depending on the underlying strategies and objectives that prompt the issuance of additional shares. Existing and potential investors must be cognizant of both the potential challenges and opportunities that share dilution may present to make informed investment decisions.
Archives: What is depreciation?
In accounting and finance, understanding how to properly manage and report asset depreciation is essential for any business. This knowledge not only ensures compliance with legal and financial reporting requirements but also provides managers and stakeholders with accurate insights into a company’s financial health. By spreading an asset’s purchase cost over its useful life, businesses can reflect a more realistic asset valuation on their financial records and can make informed decisions about future investments and resource allocation.
Understanding Depreciation
Depreciation is an accounting method used for allocating the cost of a tangible asset over its useful life. This approach helps businesses account for the reduction in value of an asset as it ages and is utilized over time. It is crucial for financial planning as it provides a mechanism for businesses to recover part of the asset’s cost and reflects the wear and tear, as well as obsolescence due to technological advancements, that decrease an asset’s utility and value.
Why Depreciation Matters
The importance of depreciation in financial management can be understood from multiple perspectives:
1. Asset Valuation: Depreciation offers a systematic way of reducing the recorded cost of the asset, reflecting its current value on the balance sheet as it gets older and possibly less productive.
2. Expense and Revenue Matching: By matching the depreciation expense with the revenues that the asset helps generate, businesses can get a more accurate picture of their profitability. This matching principle is a fundamental aspect of accrual accounting.
3. Tax Implications: Depreciation can significantly influence a company’s taxable income. Claiming depreciation expenses as deductions can lower taxable income, thereby reducing the overall tax liability.
Methods of Depreciation
Choosing the appropriate method of depreciation is crucial as it can impact financial results and tax obligations. Here’s a closer look at the different methods:
Straight-Line Method:
This is the simplest and most commonly used method. It divides the asset’s cost evenly across its useful life span. The formula applied is:
(Initial Cost – Salvage Value) / Useful Life in Years.
Declining Balance Method:
This is an accelerated depreciation method that applies a higher depreciation rate earlier in the asset’s life, which gradually declines over time. It is suitable for assets that rapidly lose their value.
Units of Production Method:
This method allocates depreciation based on actual usage or output, making it ideal for machinery and vehicles. Depreciation is high when the output level is high, and it tapers off when the asset is less used.
Sum-of-the-Years-Digits Method:
This approach also allocates more depreciation in the early years of an asset’s life and less in later years. It uses a decreasing fraction to calculate depreciation, ensuring that older assets reflect less depreciation.
Factors Influencing Depreciation
Several key factors affect how depreciation is calculated and reported:
Initial Cost: This includes the purchase price of the asset and any other expenses necessary to prepare the asset for use, such as installation and transportation fees.
Useful Life: An estimate of how long the asset will be productive within the business. This estimation can be influenced by factors such as industry standards, technological changes, and asset usage patterns.
Salvage Value: The anticipated value of the asset at the end of its useful life. This is what the business expects to recover when the asset is sold or disposed of.
Depreciation Rate: The rate at which an asset’s value is depreciated. This rate varies depending on the chosen method of depreciation and can significantly impact financial reporting and tax calculations.
Depreciation in Financial Statements
Depreciation has a marked effect on various financial statements, providing insights into asset value, revenue, expenses, and overall financial health:
On the balance sheet, depreciation affects the book value of assets. By allocating a portion of the asset’s cost as an expense, the value of tangible assets is adjusted, reflecting their diminishing utility over time.
In the income statement, depreciation is recorded as an expense, which reduces net income. As a non-cash expense, it represents neither inflows nor outflows of cash but impacts profitability by aligning costs with the generated revenues.
Even though depreciation doesn’t impact cash flow directly by reducing net income, it can influence tax obligations and subsequent cash flow, given that the resulting lower taxable income often results in reduced taxes.
For businesses navigating the complexities of accounting and finance, understanding depreciation is vital. It ensures capital investments are accurately represented on financial records, which in turn supports strategic financial planning, operational decision-making, and regulatory compliance.
For more detailed information and expert guidance on accounting and finance topics, consider resources such as Investopedia or consult with a certified accountant. A comprehensive understanding of how depreciation works is crucial for sound financial reporting and planning, ensuring that a business’s finances accurately mirror its operational realities.
Categories
- Uncategorized
 (59)
Recent Comments